
Quant / Portfolio
Monte Carlo Simulation & Markowitz Portfolio Optimization
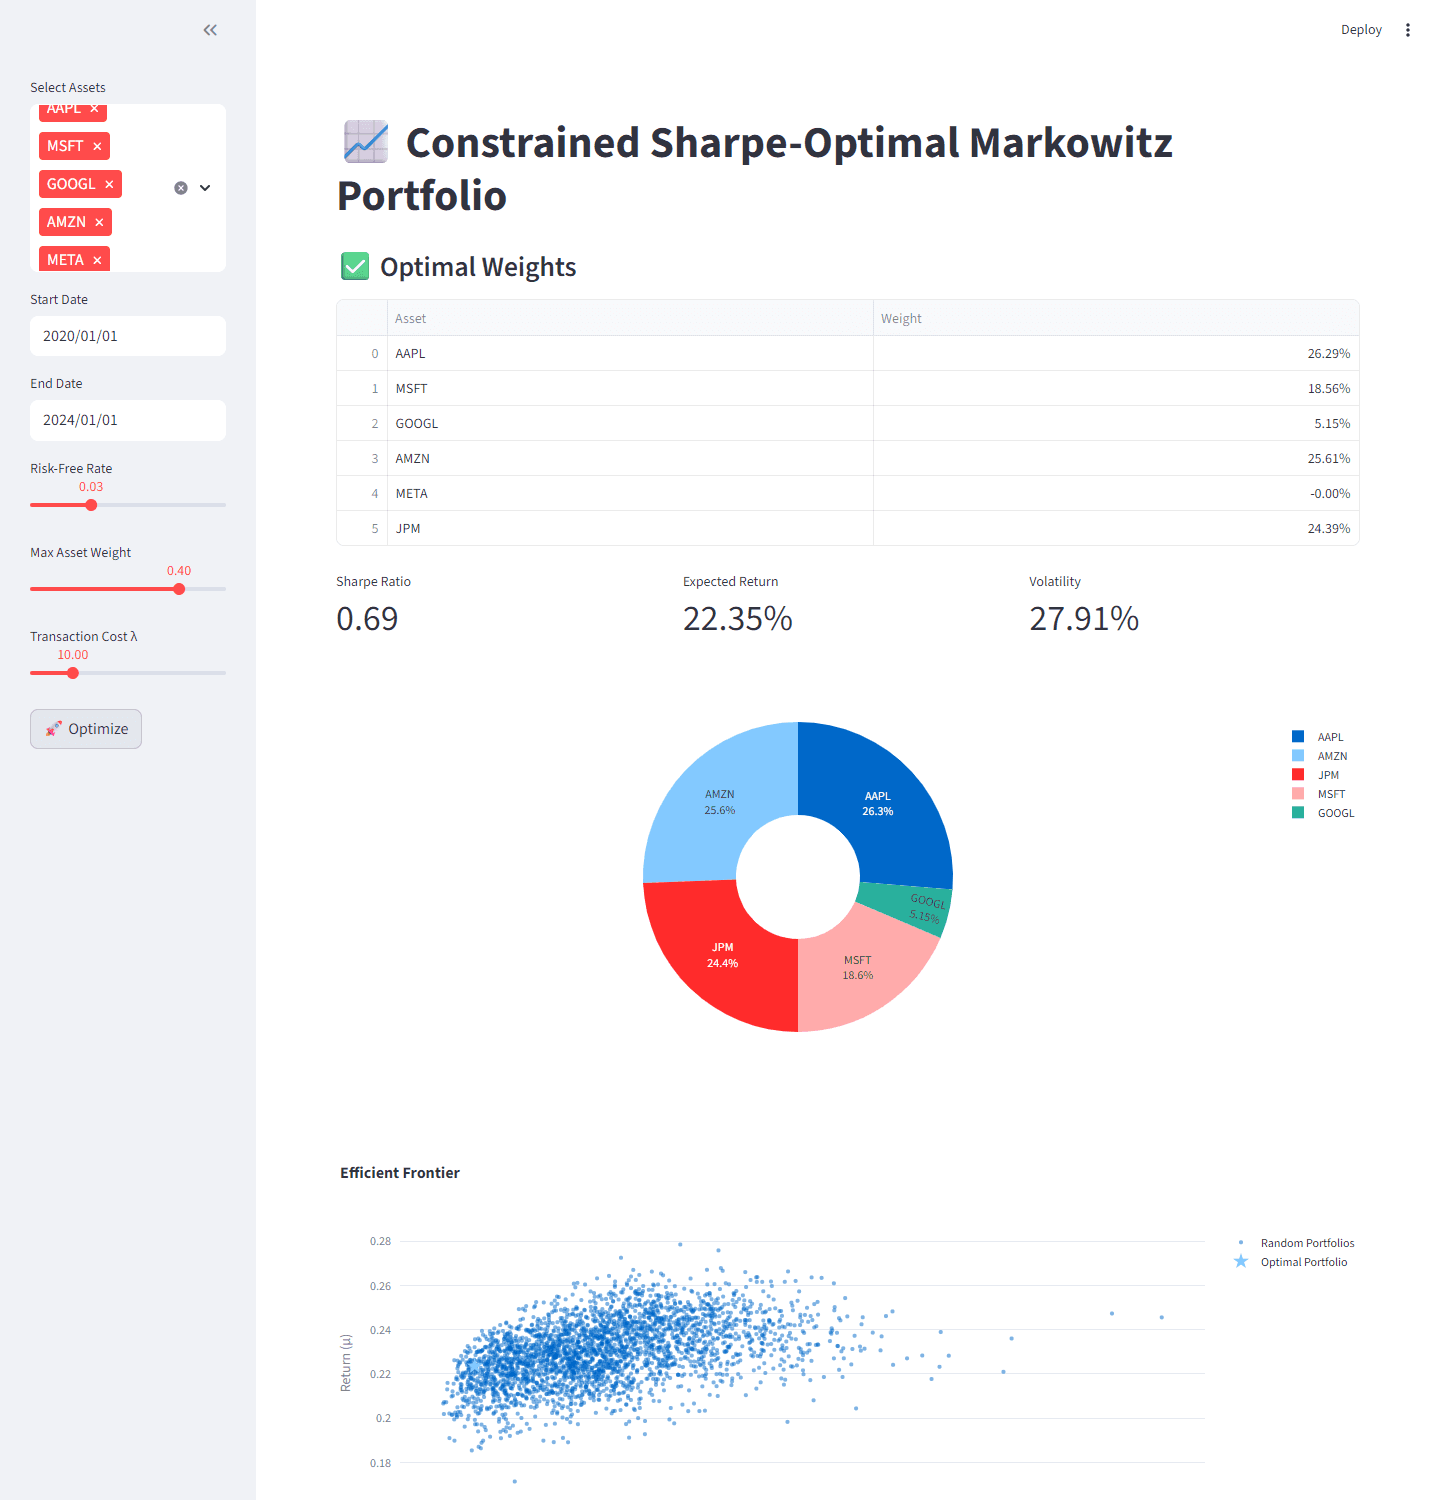
Simulated price paths and a mean-variance efficient frontier for a basket of assets.
[01] problem
Estimate the risk and return of a portfolio, then choose weights that make the best risk/return trade-off.
[02] approach
- 01Monte Carlo simulation of asset price paths and portfolio returns estimates expected return, volatility and Value at Risk.
- 02Markowitz mean-variance optimization builds the efficient frontier.
- 03The maximum-Sharpe and minimum-variance portfolios are picked off the frontier.
[03] what's interesting
- Simulation gives the risk view, and optimization uses it to choose the weights.
[04] stack
- Python
- NumPy
- Pandas
- SciPy
- Matplotlib
- cvxpy
- Streamlit
- Plotly